
TL;DR

Get your next haul delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Which? has outlined five winter hazards that may leave homeowners paying some costs themselves: storms, flooding, frozen pipes, boiler breakdowns and rodents. Its review of 72 policies found notable differences in cover, including for gradual groundwater flooding and accidental damage. Policy terms, exclusions and optional extras determine what a homeowner can claim.
Which? has warned homeowners to check their policy exclusions and optional extras for five winter hazards: storms, flooding, frozen pipes, boiler breakdowns and rodents. Its review of 72 home insurance policies found that some types of damage are less consistently covered than others, so a household may face costs even when it holds buildings or contents insurance.
The consumer group’s analysis of policies from 30 providers, conducted in the summer, found that just 25% included accidental damage cover. Standard policies generally cover storm damage, Which? said, but may exclude damage linked to wear and tear or poor maintenance. For example, a claim could be rejected if rain enters through a roof that has not been properly maintained. Damage to outdoor belongings can also depend on whether they were secured and on the policy’s limits for items kept outside.
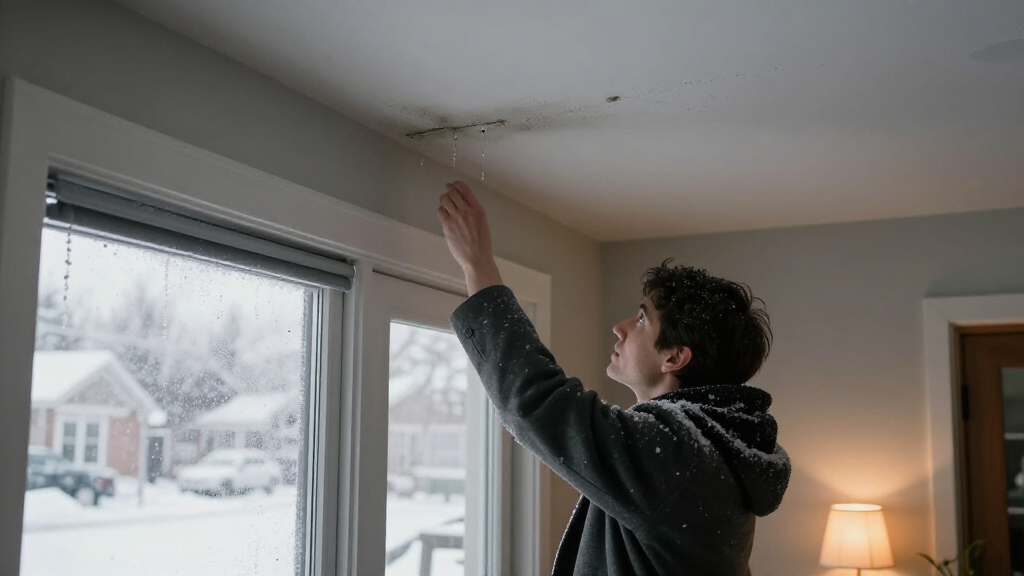
Flood cover is generally included with buildings insurance, according to Which?, but the source of the water matters. The group found that 42% of policies covered gradual groundwater flooding, in which water builds up beneath a property over time. For frozen pipes, cover was more common: 99% of the policies reviewed paid for damage to pipes caused by freezing or sudden temperature changes. Exclusions can still apply, including where a home is unoccupied or damage results from poor maintenance, corrosion or inadequate sealant.
Emergency help and equipment breakdown are separate considerations. Only 18% of the reviewed policies included home emergency cover, which can arrange a tradesperson for urgent problems such as a leak; most offered it as an optional extra. Which? said boiler cover may help with repairs and may include an annual service, while the terms for leaks vary. Rodent removal is usually associated with home emergency cover: among policies offering it as an optional extra, 97% included vermin and pest treatment or removal, the analysis found.
Where Winter Claims Can Fall Short
The findings matter because having home insurance does not by itself establish that every winter-related cost is covered. Cause, maintenance and policy wording can affect whether an insurer pays for damage, emergency assistance or the original equipment failure. A household could, for instance, have cover for damage caused by a burst pipe but not for a separate service visit to address the leak.
The possible costs extend beyond repairs. Which? said insurers generally cover cleaning and repairs after external flooding, and may pay for temporary accommodation if a property becomes uninhabitable. Contents cover may apply to belongings damaged by floodwater. But gradual groundwater accumulation is less consistently covered in the policies reviewed, making it important for residents to check the specific wording rather than assume every type of flood is treated alike.
Preparation can also affect losses. Which? advises securing outdoor belongings and bringing valuable items inside when severe weather is expected. That is practical guidance from the consumer group, not a guarantee that taking those steps will make a particular claim eligible; the insurer’s policy terms remain decisive.
What the Policy Review Found
Which? framed its report around a warning from the Association of British Insurers (ABI) for homeowners to prepare for strong winds and heavy rain linked in the article to a forecast super El Niño. The source does not establish that the weather pattern will produce a particular level of UK damage; it presents the risk as a forecast and reason to check cover ahead of winter.
The report cited ABI figures showing that claims for weather-related damage to UK homes and possessions exceeded £200 million between January and April 2026. The ABI said this was the first time claims had passed that level for that period. Which? also reported that the UK experienced seven named storms in the preceding autumn and winter. Those figures describe reported past claims and storms; they do not predict the cost or frequency of the coming season.
For rodent risks, Which? cited Saga research that found 38% of homeowners had encountered mice at their property and 20% had seen rats. The report said 15% wrongly believed standard home insurance covered pest removal. These survey findings speak to reported encounters and beliefs, while the policy review addresses the terms of the products it examined.
“The ABI is urging homeowners to prepare for strong winds and heavy rain.”
— Association of British Insurers, as reported by Which?
Policy Terms Shape Each Claim
The Which? review covers 72 policies from 30 providers; it does not establish the terms of every policy available or say whether a particular reader’s claim would be accepted. Coverage depends on the individual contract, the facts of the damage and any exclusions or conditions. The report does not name all reviewed policies in the supplied material.
The source also does not identify a specific forecast for the coming winter or establish that a super El Niño will cause more UK storms. How much damage any household faces, whether a boiler or pipe failure qualifies for a claim, and whether gradual groundwater flooding is covered all remain dependent on events and policy wording.
Check Cover Before Cold Weather
Which? advises homeowners to read their policy documents for exclusions, limits and conditions before making assumptions about winter cover. They can check whether accidental damage, home emergency assistance, boiler repairs and pest treatment are included or sold separately, and whether the policy distinguishes between external flooding and gradual groundwater build-up.
Homeowners can also take the preventive steps raised in the report: maintain roofs and plumbing, secure or bring in valuable outdoor items when storms are forecast, and check any requirements that apply when a property is left unoccupied. If damage occurs, the report’s guidance is to check the policy and contact the insurer to establish what evidence and claim steps are required. The source does not give a universal claims deadline or process, so those details must be confirmed with each insurer.
Key Questions
Does standard home insurance cover storm damage?
Which? says buildings insurance should generally cover damage from hail, wind, rain, snow and ice. Wear and tear or poor maintenance may be excluded, and outdoor belongings may have separate conditions.
Does home insurance cover all types of flooding?
Flood cover is usually included with buildings insurance, according to Which?, but gradual groundwater flooding is less consistently covered. Its review found that 42% of the policies reviewed covered damage from gradual groundwater build-up.
Are frozen pipes covered?
Which? found that 99% of policies it reviewed paid for damage to pipes caused by freezing or sudden temperature changes. Exclusions may apply in cases involving an unoccupied home or poor maintenance.
Will insurance pay to remove mice or rats?
Rodent removal is usually included in home emergency cover, rather than assumed to be part of standard home insurance. Which? found that 97% of the reviewed policies offering that cover as an optional extra included pest or vermin treatment or removal.
What should homeowners check before winter?
Check the policy’s terms for accidental damage, flood sources, frozen pipes, boiler repairs and emergency assistance. Also review maintenance and unoccupied-home conditions, plus any limits for belongings kept outside.
Source: rss
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.